




EDITOR’S NOTE: Each month, RVBusiness will post a monthly performance report provided by Lightspeed, a Dealer Management System (DMS) provider for the RV and other recreational industries. Each report is designed to provide monthly insights into the RV sector, highlighting performance trends in parts, service and sales across dealerships nationwide — drawing from data provided by all of Lightspeed’s dealer partners.
The October 2026 Dealer Financial Snapshot (vs. October 2025) delivers the most difficult results of the year, with the United States posting an -8.9% overall combined decline — surpassing August’s -5.2% as the deepest monthly drop of 2026. Every region finished in negative territory, every department declined nationally, and the brief signs of life that surfaced in September’s data largely evaporated. One factor worth weighing: October was the final full month before the midterm elections, and big-ticket discretionary purchases have historically softened when consumers face that kind of uncertainty — a dynamic that may have amplified pressures the market was already feeling.
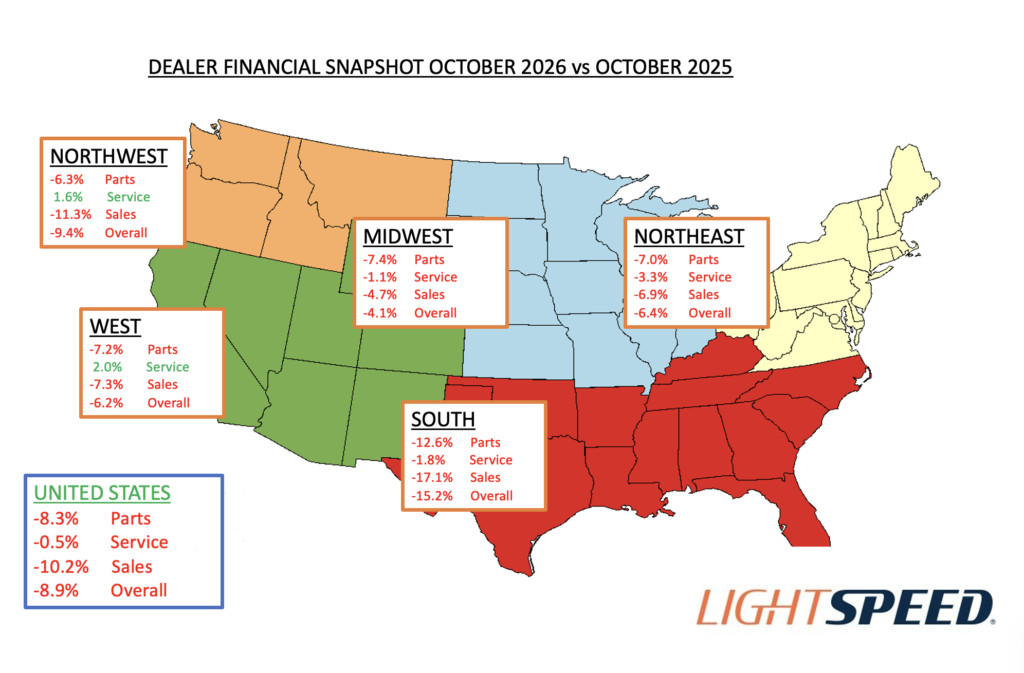
At the national level, Sales fell -10.2%, the first double-digit national sales decline of the year and a deepening of the slide that began in late summer. Parts dropped -8.3%, erasing September’s surprising +5.0% gain and suggesting that month’s rally reflected timing rather than a genuine turn. The steadying influence was Service, which held nearly flat at -0.5% — and with 122 dealers up against 132 down, the department remained the closest thing to solid ground in October’s data.
Regionally, the Midwest once again proved the most resilient region in a down month, declining -4.1% overall — the mildest result in the country. Service slipped just -1.1%, Sales fell -4.7%, and Parts declined -7.4%. This marks the second time in three months the Midwest has held the smallest decline of any region, and its steadiness has become one of the quieter consistent threads in this year’s data.
The West posted a -6.2% overall decline but showed genuine improvement from September’s -10.9% result. Service rose +2.0% — the best service result of any region, returning to the growth pattern the region had sustained through much of the summer — and 51% of the region’s dealers finished the month up in service. Sales fell -7.3% and Parts declined -7.2%, but the region’s direction, at least, was positive.
The Northeast declined -6.4% overall, giving back much of September’s near-recovery. Sales fell -6.9%, Parts dropped -7.0%, and Service slipped -3.3% — though the region’s service dealers were nearly evenly split, with 49% posting gains. After the dramatic swings of late summer, the Northeast’s October result lands closer to the middle of the pack than the bottom, a modest consolation.
The Northwest fell -9.4% overall, surrendering its September distinction as the only region in positive territory. Sales dropped -11.3% and Parts declined -6.3%. Service rose +1.6%, one of only two positive departmental results anywhere in the country, and 57% of the region’s service dealers finished the month up — the strongest service showing nationally. But the region’s sales-floor reversal continues the whiplash pattern that has defined its entire year.
The South endured its second consecutive difficult month, falling -15.2% overall — the steepest decline of any region. Sales plunged -17.1%, with just 40% of the region’s dealers posting gains, and Parts fell -12.6%, reversing the two-month parts surge that had been the region’s bright spot. Service held to a -1.8% decline, and notably, 51% of the region’s service dealers still finished the month up. For a region that spent the first half of the year as the industry’s most reliable performer, the back-to-back downturn is the most significant regional shift of 2026.
From a dealer count perspective, October’s distribution confirms the breadth of the month’s weakness. Sales was the most lopsided, with 124 dealers down versus 95 up. Parts finished at 141 down versus 99 up, the widest negative parts gap of the year. Service, once again, came closest to balance at 132 down and 122 up — with a majority of dealers up in three of the five regions, underscoring the department’s role as the industry’s shock absorber.
Overall, October’s results close out the pre-election stretch on a sobering note — but the calendar itself may offer some context. Election seasons have a history of putting large discretionary purchases on hold, and an RV is about as large and discretionary as consumer purchases come. If even part of October’s sales weakness reflects buyers waiting for clarity rather than walking away altogether, some of that demand could resurface as the uncertainty fades. The service bays tell a similar story from a different angle: owners are keeping their units maintained and on the road, which suggests engagement with the lifestyle remains intact even as new purchases stall. None of that is guaranteed to translate into a November rebound — affordability pressures and the broader economic picture haven’t gone anywhere — but as the industry heads into the final two months of the year, the question is whether October marked the bottom of a cycle or simply a pause before one more leg down. The next snapshot should offer the first real answer.
For any questions or to explore additional data offerings from Lightspeed, contact Jeremy Johnson, associate director of OEM Business Development, at Jeremy.Johnson@lightspeeddms.com.